11. Which of the following statements is true? (A)In the long run, the average cost curve is always downward sloping. (B) In the long run, the quantities of all inputs are fixed. (C)In the long run, the firms' fixed costs are greater than its variable costs. (D)In the long run, all costs are variable costs.
 阿摩線上測驗
登入
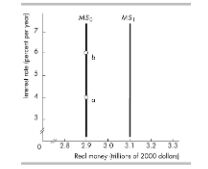 (A)increases; increases (B) increases; decreases (C)decreases; increases (D)decreases; decreases