所屬科目:研究所、轉學考(插大)◆會計學
i. Operating activities.
ii. Investing activities.
iii. Financing activities.
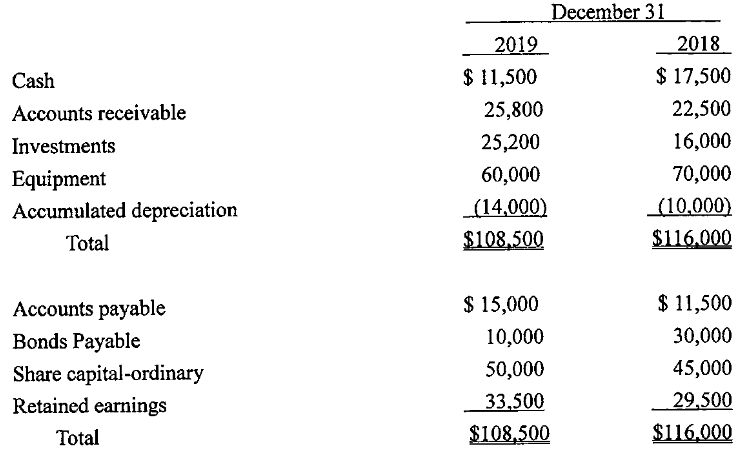
一、(16%) Taipei Company's comparative statements of financial position are presented below.Additional information: 1. Net income was $20,000. Dividends declared and paid were $16,000. 2. Equipment which cost $10,000 and had accumulated depreciation of $3,200 was sold for $3,600. 3. All other changes in non-current account balances had a direct effect on cash flows, except the change in accumulated depreciation. Instruction II. Compute free cash flow.
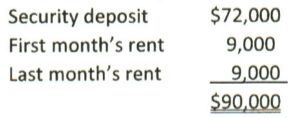
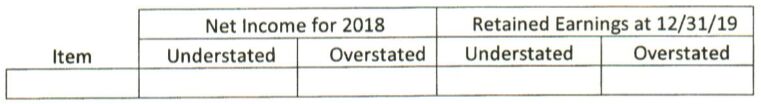
二、(24%) Suppose you are the internal auditor of Taipei Company. While reviewing the company's records for 2018 and 2019, you discover that no adjustments have yet been made for the items listed below. Items: 1. Interest income of $15,000 was not accrued at the end of 2018. It was recorded when received in March 2019. 2. A equipment costing $9,000 was expensed when purchased on September 1, 2018. It is expected to have a 6-year life with no residual value. The company typically uses straight-line depreciation for all fixed assets. 3. Research costs of $36,000 were incurred early in 2018. They were capitalized and were to be amortized over a 6-year period. Amortization of $6,000 was recorded for 2018 and $6,000 for 2019. 4. On February 1, 2018, Taipei leased a machine for 6 years at a monthly rental of $9,000. On that date, the company paid the following amounts, which were expensed when paid. 5. The company received $32,000 from a customer at the beginning of 2018 for services that it is to perform evenly over a 4-year period beginning in 2018. None of the amount received was reported as unearned revenue at the end of 2018. 6. Merchandise inventory costing $20,000 was in the warehouse at December 31, 2018, but was incorrectly omitted from the physical count at that date. Taipei company uses the periodic inventory method. Instructions Indicate the effect of any errors on the net income figure reported on the income statement for the year ending December 31, 2018, and the retained earnings figure reported on the statement of financial position at December 31, 2019. Assume all amounts are material and ignore income tax effects. Using the following format , enter the appropriate dollar amounts in the appropriate columns. Consider each item independent of the other items. It is not necessary to total the columns on the grid.
I. 所適用之毛利率 (1)
II. 失火日之存貨價值 (2)
I. 2018 年度應付公司債的利息費用 (3)
II. 2018 年底應付公司債的帳面金額 (4)
III. 2019 年度應付公司債的利息費用 (5)
IV. 2019 年底應付公司債的帳面金額 (6)
3. 台北公司於 2019 年 1 月 1 日以每股 $25 投資三峽公司 2,000,000 股,占該公司股權 25%,購買時並支付手續費用 $100,000,三峽公司 2019 年度之淨利為 $20,000,000,預計發放之現金股利為每股 $1.6,股票股利為每股 $1.2,除息日在 2020 年 1 月 10 日。 試求: 台北公司長期股權投資於 2019 年 12 月 31 日之帳面金額 (7)
I. 2019 年初備抵呆帳餘額 (8)
II. 台北公司呆帳率 (9)
I. If the ending inventory is to be valued at approximately lower-of-average-cost-or-net realizable value, the cost ratio should be (10)
II. The ending inventory at retail should be (11)
III. The approximate cost of the ending inventory by the conventional retail method is (12)
 阿摩線上測驗
登入